


A supplier offers a near-net blank that cuts the buy-to-fly ratio in half. The proposal sounds like an immediate saving: less metal purchased, fewer chips, and less rough machining. But the finished-part quote is higher because tooling, setup, inspection, and order quantity changed at the same time.
Buy-to-fly ratio compares the mass of purchased material with the mass of the finished component. It is a useful measure of material utilization, especially for aerospace parts machined from expensive stock. It is not, by itself, a complete measure of manufacturing cost, delivery risk, or environmental impact.
Calculate the Ratio Without Hiding the Boundary
For a clearly defined material input and finished part, the calculation is purchased mass divided by finished mass. A 10 kg blank that produces a 2 kg component has a buy-to-fly ratio of 5:1. The corresponding mass utilization is 20%, and the difference between blank and component mass is 8 kg.
This hypothetical calculation does not establish that all 8 kg becomes saleable chips. Some material may remain as reusable offcuts, and some can be lost through sawing, processing, or rejected work. Separate those categories if the purpose is cost or waste analysis.
| Illustrative input | Calculation | Result |
|---|---|---|
| Purchased blank: 10 kg; finished part: 2 kg | 10 / 2 | 5:1 buy-to-fly ratio |
| Finished mass as a share of blank mass | 2 / 10 × 100 | 20% utilization |
| Mass not retained in this component | 10 − 2 | 8 kg to classify, not automatically scrap revenue |
State where the numerator begins. Is it the mill product purchased for the order, the cut blank entering the CNC machine, or material allocated to one part from a shared sheet? Each boundary can support a useful analysis, but comparing different boundaries produces a misleading improvement.
The parent discussion of aerospace manufacturing cost covers the broader cost structure. This article isolates the mass calculation and then reconnects it to the purchasing decision.
One Part and One Production Batch Tell Different Stories
A nominal blank-to-part ratio describes a planned route. A batch calculation can also expose rejected parts, setup pieces, and material that never became deliverable product. Label the metric clearly rather than presenting the two as interchangeable.
Suppose a development order consumes ten 10 kg blanks, but only eight 2 kg parts are accepted. The nominal machining ratio remains 5:1 for an individual successful part. The batch purchased-to-accepted mass ratio is 100/16, or 6.25:1. Both figures are correct for their stated boundaries.
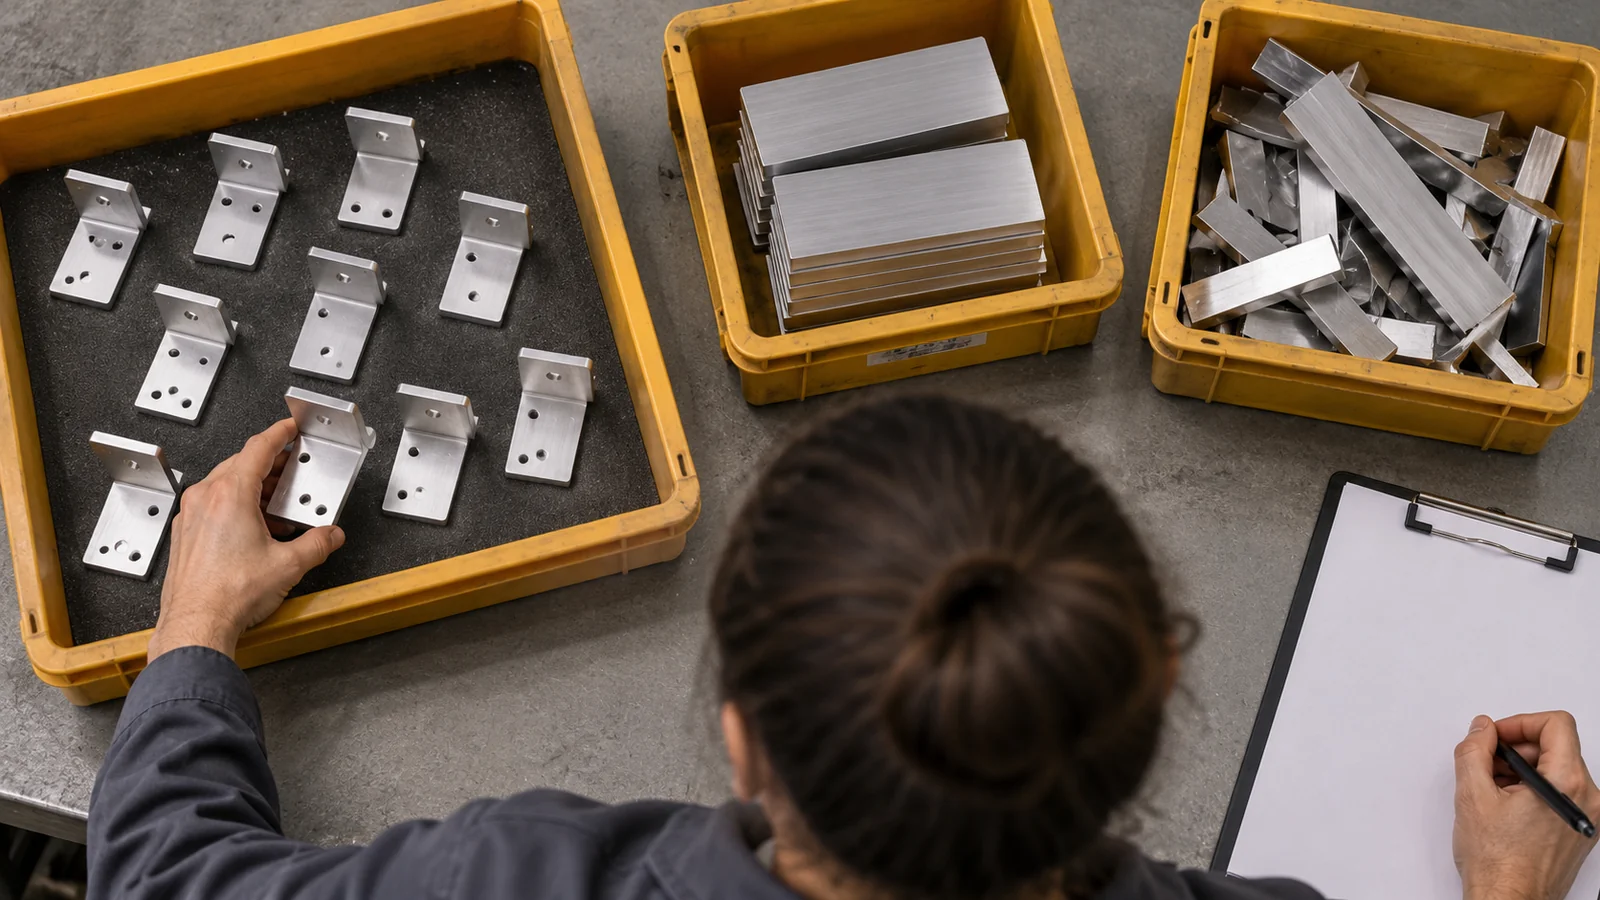
If two unused blanks remain in inventory, they should not automatically be treated as consumed scrap. If an offcut is allocated to another order, avoid crediting the same material twice. A simple material ledger often produces a more trustworthy analysis than a complicated calculator fed with inconsistent inputs.
Batch size also affects the economics of setup and first-article work. The mass ratio may stay constant while cost per accepted part changes substantially. This is one reason a production route that is attractive for hundreds of components may be unsuitable for six prototypes.
The Cheaper Route Can Have the Worse Ratio
Use a cost model with explicit categories: material purchase, setup and tooling, processing, inspection, finishing, expected rework or rejection, and any recoverable scrap credit. Do not subtract scrap mass directly from purchased mass and call the result an improved buy-to-fly ratio.
The following example uses arbitrary cost units for comparison only. It is not a Jucheng Precision quotation, a market price, or a predicted production result. Both routes are assumed to deliver the same accepted geometry and required evidence.
| Cost per accepted part | Route A: machined stock | Route B: near-net blank |
|---|---|---|
| Material purchase | 200 | 140 |
| Setup and tooling allocation | 50 | 180 |
| Processing | 180 | 100 |
| Inspection and finishing | 70 | 90 |
| Scrap credit | −20 | −5 |
| Total illustrative cost | 480 | 505 |
Route B purchases less material and requires less processing, yet its allocated tooling cost outweighs those savings at this assumed quantity. At a different quantity, the ranking could reverse. Calculate that change using the actual fixed and variable costs rather than extrapolating from material utilization alone.
Scrap credit needs equal care. Recovery value depends on alloy segregation, contamination, handling, local terms, and who owns the chips. Recovered material value is generally not the same as the purchase price of certified stock. Obtain the relevant commercial terms before using the credit in a sourcing decision.
Compare Manufacturing Routes on Equal Terms
Machining from plate or bar offers flexibility and can avoid dedicated forming tooling. Forgings, castings, extrusions, and additive preforms may reduce excess material for suitable geometries, but each introduces its own product requirements and qualification considerations.

Airbus describes titanium additive manufacturing as a route to reducing material use for selected aircraft components. That example supports evaluating alternative routes; it does not show that additive manufacturing is automatically cheaper or approved for every part.
Hold the finished requirement constant. Compare the same drawing revision, accepted quantity, material properties, surface condition, tolerances, and documentation. Include any additional machining needed to finish a near-net preform. A rough preform price is not comparable with a completed, inspected component price.
For a machined route, the aerospace CNC machining scope should identify the stock form and critical features. If a proposed alternative changes material structure or design assumptions, it needs engineering review before commercial comparison becomes meaningful.
Five Practical Levers Before Changing the Process
Reduce avoidable stock allowance
Check whether the blank size reflects real clamping, cleanup, and distortion needs. Excess allowance adds both purchase mass and cutting time. Insufficient allowance can instead cause setup failure or rejection, so the reduction must be justified.
Improve layout without violating orientation
Multi-part nesting can reduce allocated material, but directional requirements, saw access, and identification must survive the change. Sheet yield is not a valid reason to ignore a controlled grain direction.
Separate development needs from production habits
A prototype may require flexible geometry changes; production may justify dedicated tooling. Revisit the route when the design stabilizes rather than automatically repeating the first machining plan forever.
Review material that exists only for workholding
Temporary tabs and sacrificial features can be useful. Evaluate whether an alternative fixture reduces them without creating extra operations or unreliable clamping. Less stock is valuable only if accepted-part yield remains under control.
Look at geometry before chasing a better ratio
A pocket or thin wall may be functionally necessary. Removing it to improve a metric can increase finished mass or harm performance. The separate thin-wall machining discussion addresses manufacturing stability; the design authority must decide which features can change.
Turn the Ratio into a Useful RFQ Question
Ask suppliers to state proposed stock dimensions, allocated input mass, finished mass, and the boundary used for the ratio. Request tooling allocation, expected order quantity, finishing scope, inspection package, and exceptions separately.
For a Jucheng Precision route review, a model, controlled drawing, quantity range, and required material condition provide a useful starting point. Ask which cost drivers are sensitive to geometry or batch size, rather than requesting the lowest possible ratio without constraints.
The strongest comparison shows why a route is economical for this part at this quantity. A single utilization number cannot supply that explanation.
Quick Answers for Cost Reviews
Is a 1:1 ratio always the target?
It is an idealized mass-utilization limit for the stated boundary, not necessarily the best practical manufacturing route. Required allowances, finishing, testing, and production economics still matter.
Does recycling improve the ratio?
Recycling can change waste handling and cost recovery. It does not change the original purchased-to-finished mass ratio unless the definition or accounting boundary changes, which must be disclosed.
Can the ratio prove a lower carbon footprint?
No. Energy, material production, processing, transport, scrap treatment, and system boundaries also affect environmental comparisons. A mass ratio alone is insufficient evidence for that claim.

